Term Life Insurance
Affordable protection for 10, 20 or 30 years. Ideal for replacing income while you raise kids or pay off a mortgage.
Rose compares plans from multiple top-rated carriers to find coverage that fits your family and your budget. Straight answers, no pressure, and no cost to talk.
Every family is different. Rose explains your options in plain English and helps you choose the right mix.
Affordable protection for 10, 20 or 30 years. Ideal for replacing income while you raise kids or pay off a mortgage.
Lifetime coverage with fixed premiums and guaranteed cash value that grows over time.
Permanent coverage with cash value linked to a market index, with downside protection and flexible premiums.
Options for guaranteed income in retirement and tax-deferred growth for your savings.
Some policies include living benefits, which let you access part of your death benefit early if you face a qualifying illness or injury.
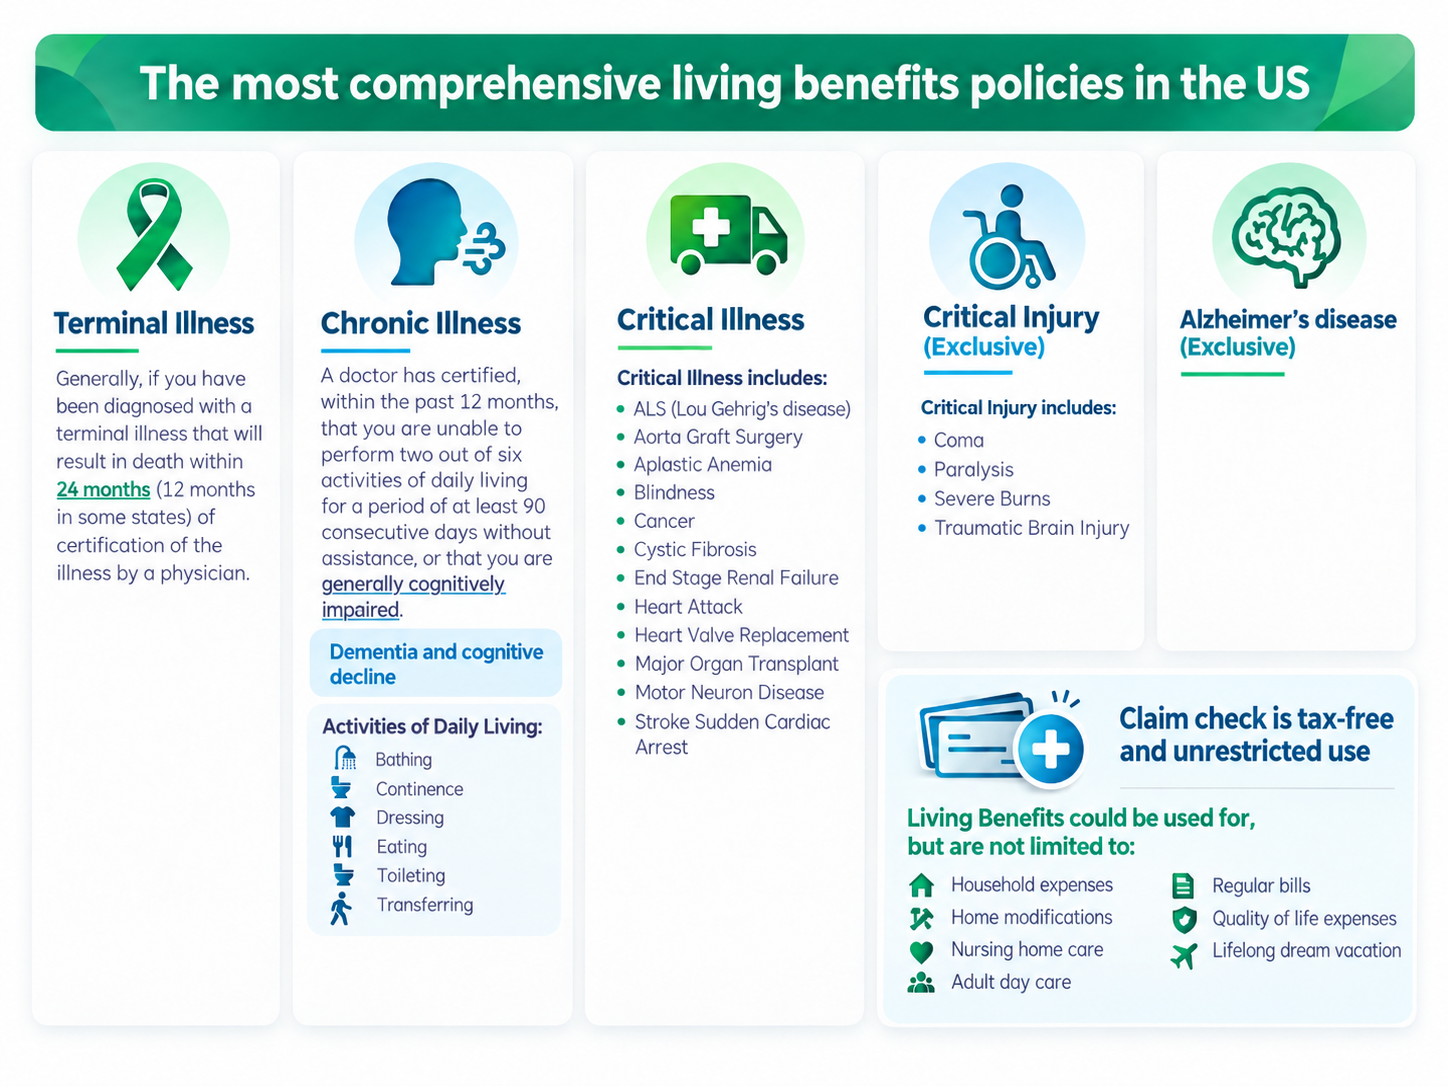
Living benefits are provided through accelerated benefit riders and depend on policy terms, eligibility and state availability. Using them reduces the death benefit.
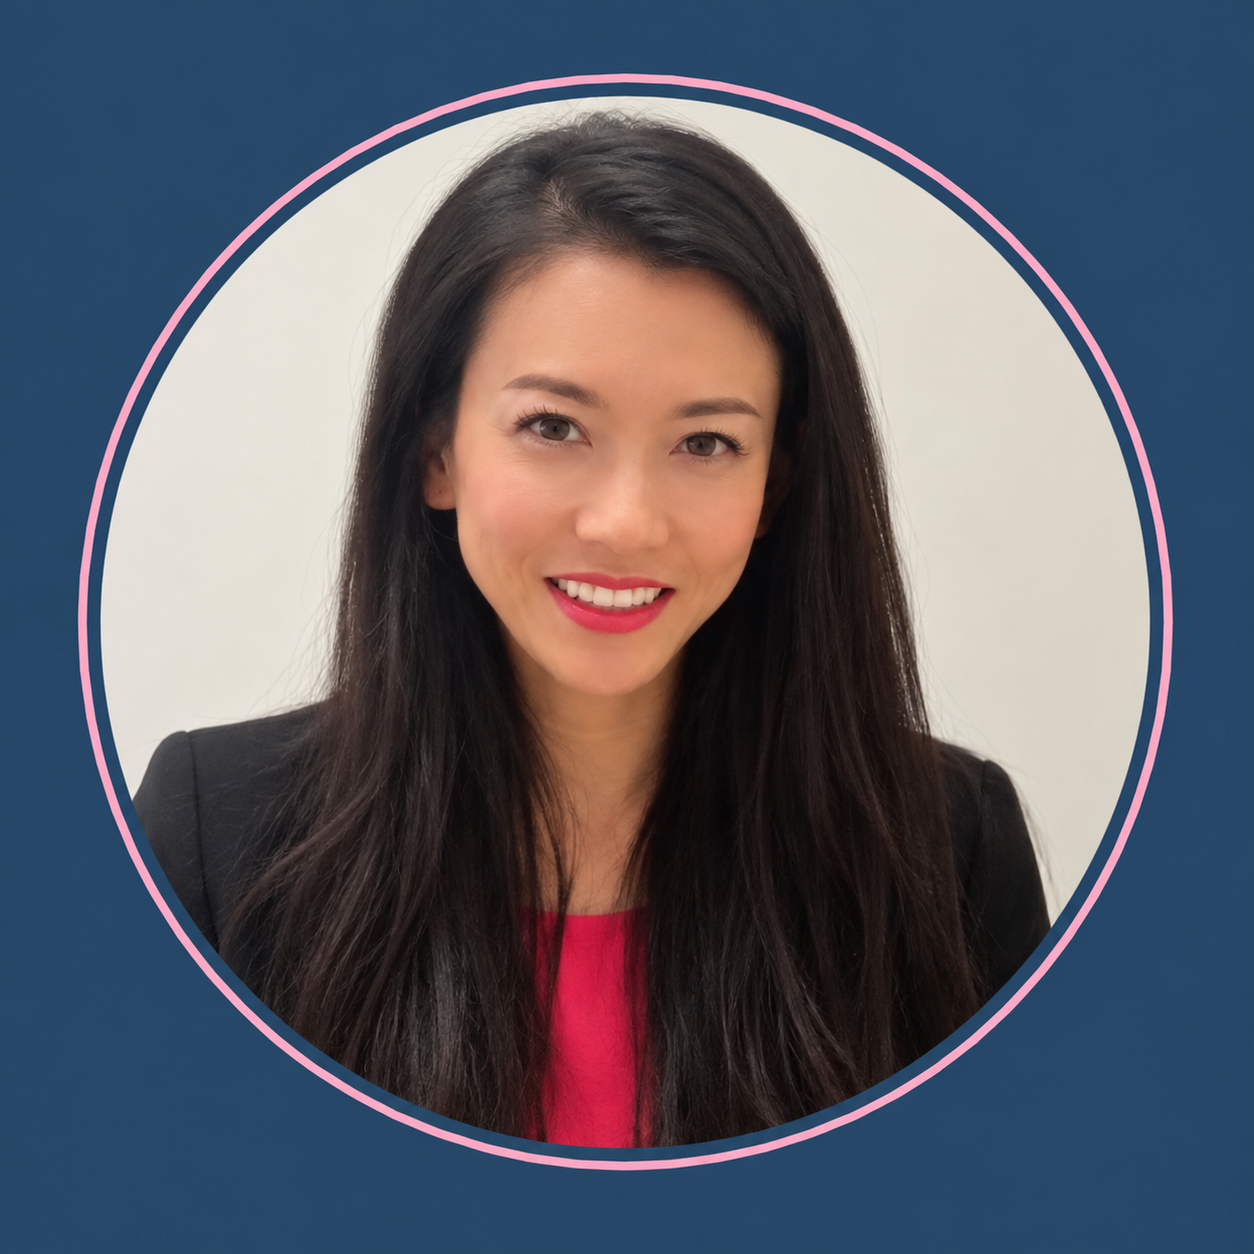
I started Financial Planning with Rose to help families make confident decisions about protecting their future. As an independent licensed agent, I'm not tied to one company. I shop the market for you and recommend what fits your needs.
As a registered nurse, I've seen first-hand how a serious illness affects a family's finances, not just their health. That's why I take the time to explain options like living benefits, so your coverage can help while you're living, not only after.
A relaxed 20-minute call to understand your family, goals and budget.
Rose shops multiple carriers and explains the best-fit plans side by side.
Apply online, often with no medical exam, and Rose handles the paperwork.
Tell Rose a little about what you're looking for and she'll get back to you. No obligation.
Prefer to talk? Call (714) 732-0388
A common starting point is 10 to 12 times your annual income, adjusted for your mortgage, debts, children's education and existing savings. Rose walks through a simple needs analysis with you so the number fits your family, not a rule of thumb.
Term life covers you for a set period, such as 10, 20 or 30 years, and is usually the most affordable. Whole life lasts your entire life and builds cash value, but costs more. Many families use term for income protection and permanent coverage for final expenses or legacy goals.
Not always. Many carriers offer no-exam or simplified-issue policies based on a health questionnaire. Whether an exam is needed depends on your age, health and coverage amount.
No. Consultations and quotes are free. Agents are paid by the insurance company when a policy is placed, so you pay only your policy premium.
Often, yes. Carriers underwrite health differently, so comparing several companies can uncover better rates or approval options than applying to just one.
Indexed universal life (IUL) is permanent life insurance that builds cash value based partly on the performance of a market index, such as the S&P 500, without being invested in the market directly. Your cash value isn't credited with index losses, but caps limit how much you can earn. You can access cash value through policy loans or withdrawals, which reduce the death benefit.
Living benefits are policy riders that let you access part of your death benefit while you're still alive if you're diagnosed with a qualifying terminal, chronic or critical illness. You can use the money however you need, such as medical bills, your mortgage or everyday expenses. Any amount you use reduces the death benefit your family receives.
An annuity is a contract with an insurance company that turns a lump sum or a series of payments into income, either now or later, often for life. Fixed and fixed indexed annuities protect your principal from market losses and grow tax-deferred. Early withdrawals may carry surrender charges and, before age 59½, a federal tax penalty.
Get a free, personalized life insurance quote in minutes. No pressure, no obligation.